
Business
Oil rises slightly ahead of potential US-Iran talks

Oil prices rose on Tuesday for the first time in five sessions as investors awaited news on possible US-Iran negotiations at the United Nations General Assembly this week after additional supplies passed through the Strait of Hormuz over the weekend.
Brent crude futures for November gained $1.14, or 1.1 percent, to $101.48 a barrel by 0317 GMT. The WTI October contract, which expires on Tuesday, rose 87 cents, or 0.9 percent, to $96.65 a barrel.
The more actively traded November contract rose 85 cents, or 0.9%, to $93.22 a barrel.
Tehran and Washington traded threats Sunday although US President Donald Trump indicated he would be open to meeting Iranian President Masoud Pezeshkian, who is likely to be in New York this week for the UN summit.”The rise in WTI and the stronger opening in Brent look like a garden-variety short-covering bounce after the recent slide, rather than a change in fundamentals,” said Tim Waterer, chief market analyst at KCM Trade.“Traders are taking some risk off the table, positioned for further downside as the diplomatic narrative plays out.”
Iran has also conveyed to mediators over the weekend its terms for returning to negotiations, Al Jazeera said, quoting Iran’s security commander, Mohsen Rezaei.
“Oil prices are going to be range-bound and sensitive to headlines until there’s either clear progress or a setback in the diplomatic efforts between the U.S. and Iran,” Waterer said.
Tensions remained high in the Middle East as Yemen’s Iran-backed Houthis announced they attacked Riyadh and a Saudi Aramco complex in Yanbu and stepped up efforts to shut off Saudi-backed forces from the Red Sea coast.
Saudi Arabia has appealed to Beijing after an increase in Houthi military activities in recent days, while China has discreetly asked Tehran to assist rein in the attacks, three Iranian sources said.
Saudi Aramco has boosted exports via the Strait of Hormuz after attacks on its East-West Pipeline halted some supplies through Yanbu. Tanker tracking data showed it loaded around 14 million barrels of its crude oil aboard seven supertankers inside the Gulf on Sunday.
“The new feature indicates the country’s eagerness to compete in the booming AI industry,” attendees remark.Supply worries are abating as exports via the Strait of Hormuz hit a six-month high and Saudi Arabia moves to repair its East-West pipeline…“Crude implied volatility dropped 3.3% to 50.39 but remains elevated historically,” Saxo Bank analysts stated in a client note.
Separately, an armed group shut valve seven on Libya’s Sharara crude pipeline to Zawiya port on Monday, causing a major drop in production at the Sharara oilfield, Libya’s National Oil Corporation said in a statement.
Production from the field has plummeted by roughly 200,000 barrels per day and is now 100,000 bpd to 105,000 bpd, two engineers at the field told Reuters.
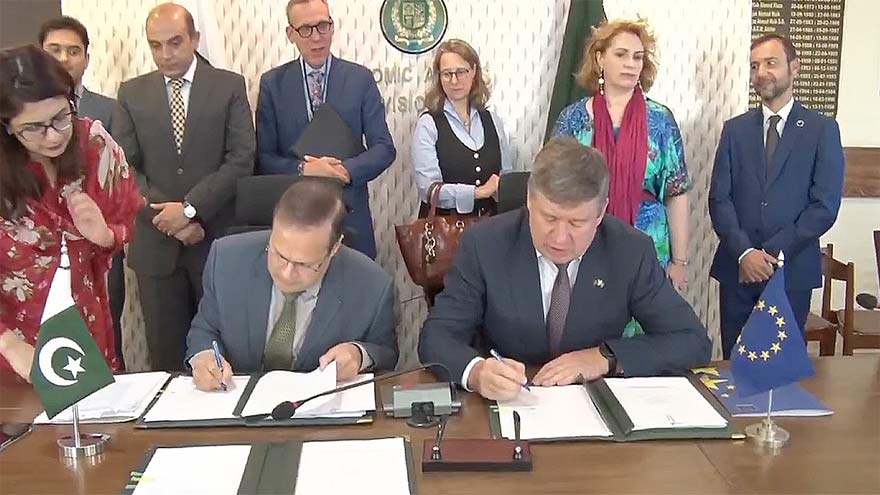
The European Union (EU) and Pakistan signed three grant agreements for €65 million ($74.6 million) on Monday that would assist Islamabad attract international investment, deliver renewable energy to off-grid populations in its northwest and improve access to justice, the information ministry said.
The awards are financed through the EU’s Multiannual Indicative Program 2021-2027 and are part of Global Gateway, the European Commission’s infrastructure investment agenda.
The plan intends to mobilize up to €300 billion ($344.6 million) in public and private investment globally in the period 2021-2027 in sectors such as technology, energy and transport.
The Pakistani government is focusing on attracting more foreign investment as it tries to achieve sustainable economic growth. In 2023 it created the Special Investment Facilitation Council, a hybrid government entity comprising both civilian and military leaders, to attract international investment to vital economic sectors.
Addressing the signing, EU Ambassador Raimundas Karoblis said: “These agreements reflect the EU’s commitment to Pakistan’s economic development and investment ambitions under our flagship Global Gateway initiative.”
The first program attempts to promote foreign investment by improving the taxation structure in Pakistan and by boosting the long-term financial planning of the government.
The second would increase renewable energy in rural villages in Khyber Pakhtunkhwa (KP) province that are not connected to the national grid. It will also train to attract private investment into the energy industry of the province.
The third, building on EU assistance before, will help individuals in Khyber Pakhtunkhwa and Balochistan access police, prosecution services, courts and legal aid.
Both provinces share a border with Afghanistan and have bore the brunt of extremist strikes in Pakistan in recent years. Research and data platform South Asia Terrorism Portal recorded 176 attacks and 438 deaths in Balochistan in July, the highest number of violence in the month, while KP recorded 143 occurrences and 244 fatalities during the period.
The same program will help Pakistan’s most populous and industrialized provinces, Punjab and Sindh, to expand alternative and commercial conflict resolution with the declared purpose of making them more appealing to European and other corporations seeking to invest.
The EU’s development partnership with Pakistan focuses on economic development, climate resilience, governance, rule of law, human rights and sustainable management of natural resources, the statement stated. The European Union (EU) and Pakistan on Monday inked three grant agreements for €65 million ($74.6 million) to assist Islamabad attract international investment, deliver renewable energy to off-grid populations in its northwest and improve access to justice, the information ministry said.
The awards are supported under the EU’s Multiannual Indicative Program 2021-2027 and are part of the European Commission’s infrastructure investment initiative, Global Gateway.
The plan intends to mobilize up to €300 billion ($344.6 million) in public and private investment globally in the period 2021-2027 in sectors such as technology, energy and transport.
The Pakistani government is focusing on attracting more foreign investment as it tries to achieve sustainable economic growth. In 2023 it created the Special Investment Facilitation Council, a hybrid government entity comprising both civilian and military leaders, to attract international investment to vital economic sectors.
Addressing the signing, EU Ambassador Raimundas Karoblis said: “These agreements reflect the EU’s commitment to Pakistan’s economic development and investment ambitions under our flagship Global Gateway initiative.”
The first program attempts to promote foreign investment by improving the taxation structure in Pakistan and by boosting the long-term financial planning of the government.
The second would increase renewable energy in rural villages in Khyber Pakhtunkhwa (KP) province that are not connected to the national grid. It will also train to attract private investment into the energy industry of the province.
The third, building on EU assistance before, will help individuals in Khyber Pakhtunkhwa and Balochistan access police, prosecution services, courts and legal aid.
Both provinces share a border with Afghanistan and have bore the brunt of extremist strikes in Pakistan in recent years. Research and data platform South Asia Terrorism Portal recorded 176 attacks and 438 deaths in Balochistan in July, the highest number of violence in the month, while KP recorded 143 occurrences and 244 fatalities during the period.
The same program will also help the most populated and industrialized regions of Pakistan, Punjab and Sindh, to increase alternative and commercial conflict resolution, with the declared purpose of making them more attractive for European and other corporations seeking to invest.
The EU’s development cooperation with Pakistan covers economic development, climate resilience, governance, rule of law, human rights and sustainable management of natural resources, the statement said.
Pakistan’s net foreign direct investment (FDI) jumped 80 percent year-on-year to $316 million in August, the country’s financial advisor said on Sunday, calling it a “positive signal” as Islamabad transitions from macroeconomic stability to investment-led, sustainable development.
The $316 million foreign investment inflows was the greatest monthly level reached by the country in the last two years, while it marked a 77 percent increase on a month-on-month basis, Khurram Schehzad, an assistant to Finance Minister Muhammad Aurangzeb, said in a post on X.
The increase was backed by better investment inflows from China, Canada and the UAE, along with a reduced repatriation and outflows, leading to a much stronger net FDI position during the month,” he said.
Pakistan’s net FDI plummeted 34 percent to $1.64 billion or 0.39 percent of gross domestic product in the Fiscal Year 2025-26 that ended in June, according to World Bank data.
This was far below the previous average of about 2 percent of GDP for Emerging Market and Developing Economies and much below the roughly 5 percent peak reported in 2008.
For policymakers, investment promotion should not cease after an investor joins the nation, said the former minister.
“It’s about shifting investment, thinking from measuring capital flows only to understanding how capital creates enduring economic capability.”
Consumer prices in Pakistan surged to 11.1 percent in August from 9.2 percent in July, exceeding the central bank’s medium-term inflation target of 5-7 percent further.
Oil prices fell to their lowest in more than a week on Monday on hopes diplomacy in the Iran war will get a chance this week amid a UN meet and as investors watched a partial recovery in shipments from Saudi Arabia despite continuous attacks by Yemen’s Houthis.
Brent crude futures and US West Texas Intermediate crude earlier on Monday dropped to their lowest since Sept. 10. Brent was at $101.71 a barrel by 0213 GMT, down $2.16, or 2.08%, after finishing 0.91% lower on Friday.
U.S. West Texas Intermediate crude fell $2.15, or 2.14 percent, to $98.15 a barrel after a 1.58 percent decline in the previous session.“The risk premium is being stripped out of oil prices on the back of hopes that a diplomatic solution to the US-Iran war may be found this week,” said Tim Waterer, chief market analyst at KCM Trade.Whether that hope will be fulfilled remains to be seen. “We’ll see how it goes.
The WTI broke a major psychological support at $100 a barrel while some investors may have rolled over their positions in the October contract a day ahead of expiry to November, said a broker in Singapore.
Iran and the US traded more threats on Sunday as the standoff continued, but President Donald Trump indicated he would be open to meeting Iranian President Masoud Pezeshkian, who is due in New York this week for the United Nations General Assembly.
Iran has informed mediators about its prerequisites for resuming talks to end the war with the US, Iran’s security chief Mohsen Rezaei said in an interview on Saturday, Al Jazeera reported.
But tensions in the Middle East remained elevated as Yemen’s Iran-backed Houthis said they struck “sensitive” locations in the Saudi capital Riyadh on Saturday with missiles and drones, as well as an Aramco facility in the Red Sea city of Yanbu, a vital oil export centre.
Three Iranian sources acquainted with the situation said China had asked Iran to assist reign in the Houthis following a plea to Beijing by Saudi Arabia after the strikes.
Houthi strikes on Saudi Aramco’s East-West pipeline have led the state energy corporation to boost exports through the Strait of Hormuz this and next month after halting some shipments through Yanbu.
That meant OPEC kingpin exports bounced up to around 4 million barrels per day (bpd) so far in September after falling to 2.4 million bpd in August, the lowest since at least 2013, according to interim statistics from analytics firm Kpler.”Oil flows in the Middle East are surprisingly resilient despite disruption to Saudi Arabia’s East-West pipeline,” JPMorgan analysts said in a note on September 18 adding the overall oil flows averaged 17.1 million bpd in the past 10 days, barely 6.1 million bpd below the 2025 average.“The most notable pivot has come from Saudi Arabia,” the experts said. Satellite data showed Saudi oil transiting the Strait of Hormuz averaged 2.9 million bpd over the preceding six days, up from just 700,000 bpd in August.

Pakistan women clinch Asian Games bronze with 31-run win over Bangladesh

Dar calls for implementation of Islamabad MoU for advancing regional stability

Trump approval falls to record low of 32pc as high costs bite, Reuters/Ipsos poll finds

ICC board meeting in India: Mohsin Naqvi gets invitation

23 people have died during the monsoon as rain-related incidents plague Punjab and KP.

Govt dedicated to resolving Balochistan issues: Dar
-
 Latest News4 months ago
ICC board meeting in India: Mohsin Naqvi gets invitation
-
 Latest News2 months ago
23 people have died during the monsoon as rain-related incidents plague Punjab and KP.
-
 Business2 months ago
Govt dedicated to resolving Balochistan issues: Dar
-
 Latest News1 month ago
‘Self-Reliance in Digital ID’: NADRA launches locally produced QR code-based National Identity Card
-
 Latest News2 months ago
Pakistan making rapid progress in robotics, AI: Shaza Fatima
-
 Latest News2 months ago
After a divorce, LHC decides that women who have been harmed by their spouses get their dower.
-
 Entertainment4 months ago
Interim bail given to YouTuber Rajab Butt in gambling app marketing case
-
 Latest News4 months ago
A meta program to monitor mouse clicks made by employees in violation of EU privacy regulations