
Business
Oil rises as fresh US, Iran confrontations ignite Middle East

Oil prices rose Monday after days of tit-for-tat strikes by the U.S. and Iran that highlighted the fragility of their interim peace deal and again slowed energy shipping through the Strait of Hormuz.
Brent crude futures were up 58 cents, or 0.8%, at $72.57 a barrel by 0207 GMT. U.S. West Texas Intermediate crude was at $70.11 a barrel, up 88 cents, or 1.3%.There is still a lot of risk in the oil industry. Still, participants seem to be preoccupied with the implications for the global balance of a continued recovery in oil flows,” ING analysts said in a note on Monday.This confidence is strange and plainly provides considerable upside risk if the supply recovery proves slow.”
Brent crude closed down 10.6% last week, its third weekly loss, after crude shipments through the strait increased last week to the greatest level since the U.S.-Israeli war on Iran started in late February.
But commerce has slowed anew since repeated attacks on ships in the strait from Thursday, including a Qatar-linked oil tanker, which prompted strikes from the U.S. and Iran in the sharpest escalation since they signed an interim peace pact.
Iran and the United States have agreed to end recent confrontations in the Gulf and resume discussions on their dispute over the Strait of Hormuz, a U.S. official said on Sunday, capping increases in oil prices.”Market will likely revisit its assumption of a quick recovery of oil supply from the Persian Gulf,” ANZ analysts said in a note.
Saudi oil company Aramco (2222.SE), opens new tab began crude oil loadings on Friday at its Ras Tanura terminal, west of the Strait of Hormuz, after they were stalled for nearly four months, as oil producers stepped up output and exports ahead of a temporary accord.
The loadings went on even after a helicopter owned by the firm crashed Sunday at Ras Tanura, killing 14 nationalities. The cause of the crash was unknown.Physical flows are constrained by tanker backlogs, infrastructure and production shut-ins. “It could take the rest of the year for supplies to get back to pre-conflict levels,” ANZ analysts warned.
Browse Topics
Pakistan’s net foreign direct investment (FDI) jumped 80 percent year-on-year to $316 million in August, the country’s financial advisor said on Sunday, calling it a “positive signal” as Islamabad transitions from macroeconomic stability to investment-led, sustainable development.
The $316 million foreign investment inflows was the greatest monthly level reached by the country in the last two years, while it marked a 77 percent increase on a month-on-month basis, Khurram Schehzad, an assistant to Finance Minister Muhammad Aurangzeb, said in a post on X.
The increase was backed by better investment inflows from China, Canada and the UAE, along with a reduced repatriation and outflows, leading to a much stronger net FDI position during the month,” he said.
Pakistan’s net FDI plummeted 34 percent to $1.64 billion or 0.39 percent of gross domestic product in the Fiscal Year 2025-26 that ended in June, according to World Bank data.
This was far below the previous average of about 2 percent of GDP for Emerging Market and Developing Economies and much below the roughly 5 percent peak reported in 2008.
For policymakers, investment promotion should not cease after an investor joins the nation, said the former minister.
“It’s about shifting investment, thinking from measuring capital flows only to understanding how capital creates enduring economic capability.”
Consumer prices in Pakistan surged to 11.1 percent in August from 9.2 percent in July, exceeding the central bank’s medium-term inflation target of 5-7 percent further.
Oil prices fell to their lowest in more than a week on Monday on hopes diplomacy in the Iran war will get a chance this week amid a UN meet and as investors watched a partial recovery in shipments from Saudi Arabia despite continuous attacks by Yemen’s Houthis.
Brent crude futures and US West Texas Intermediate crude earlier on Monday dropped to their lowest since Sept. 10. Brent was at $101.71 a barrel by 0213 GMT, down $2.16, or 2.08%, after finishing 0.91% lower on Friday.
U.S. West Texas Intermediate crude fell $2.15, or 2.14 percent, to $98.15 a barrel after a 1.58 percent decline in the previous session.“The risk premium is being stripped out of oil prices on the back of hopes that a diplomatic solution to the US-Iran war may be found this week,” said Tim Waterer, chief market analyst at KCM Trade.Whether that hope will be fulfilled remains to be seen. “We’ll see how it goes.
The WTI broke a major psychological support at $100 a barrel while some investors may have rolled over their positions in the October contract a day ahead of expiry to November, said a broker in Singapore.
Iran and the US traded more threats on Sunday as the standoff continued, but President Donald Trump indicated he would be open to meeting Iranian President Masoud Pezeshkian, who is due in New York this week for the United Nations General Assembly.
Iran has informed mediators about its prerequisites for resuming talks to end the war with the US, Iran’s security chief Mohsen Rezaei said in an interview on Saturday, Al Jazeera reported.
But tensions in the Middle East remained elevated as Yemen’s Iran-backed Houthis said they struck “sensitive” locations in the Saudi capital Riyadh on Saturday with missiles and drones, as well as an Aramco facility in the Red Sea city of Yanbu, a vital oil export centre.
Three Iranian sources acquainted with the situation said China had asked Iran to assist reign in the Houthis following a plea to Beijing by Saudi Arabia after the strikes.
Houthi strikes on Saudi Aramco’s East-West pipeline have led the state energy corporation to boost exports through the Strait of Hormuz this and next month after halting some shipments through Yanbu.
That meant OPEC kingpin exports bounced up to around 4 million barrels per day (bpd) so far in September after falling to 2.4 million bpd in August, the lowest since at least 2013, according to interim statistics from analytics firm Kpler.”Oil flows in the Middle East are surprisingly resilient despite disruption to Saudi Arabia’s East-West pipeline,” JPMorgan analysts said in a note on September 18 adding the overall oil flows averaged 17.1 million bpd in the past 10 days, barely 6.1 million bpd below the 2025 average.“The most notable pivot has come from Saudi Arabia,” the experts said. Satellite data showed Saudi oil transiting the Strait of Hormuz averaged 2.9 million bpd over the preceding six days, up from just 700,000 bpd in August.
The Pakistan Stock Exchange turned bearish in early trade on Wednesday, with the KSE-100 index dropping over 600 points.
At the start of the third session of the week, the index had fallen more than 600 points to 168,732 points. Previously on Tuesday, the benchmark index showed an upward trend, increasing by 1,421.67 points (up 0.85%) to close at 169,392.33 points compared to 167,970.66 points in the previous session.
In the ready market, the trading volume was 372,016,000 shares as against 570,472,000 shares in the previous trade and the trading value was Rs 17,210 million as against Rs 24,672 million. The market capitalization increased to Rp 18,857 billion from Rp 18,728 billion the previous day.

FM Dar arrives in New York for 81st session of UN General Assembly

Xi arrives for Trump summit with China’s trade engine in full operation

Khawaja Asif slams PTI’s Junaid Akbar for ‘Somnath’ statement ahead of protest

ICC board meeting in India: Mohsin Naqvi gets invitation

23 people have died during the monsoon as rain-related incidents plague Punjab and KP.

Govt dedicated to resolving Balochistan issues: Dar
-
 Latest News4 months ago
ICC board meeting in India: Mohsin Naqvi gets invitation
-
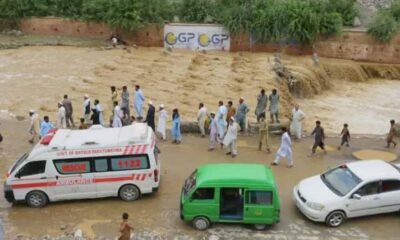 Latest News2 months ago
23 people have died during the monsoon as rain-related incidents plague Punjab and KP.
-
 Business2 months ago
Govt dedicated to resolving Balochistan issues: Dar
-
 Latest News1 month ago
‘Self-Reliance in Digital ID’: NADRA launches locally produced QR code-based National Identity Card
-
 Latest News2 months ago
Pakistan making rapid progress in robotics, AI: Shaza Fatima
-
 Latest News2 months ago
After a divorce, LHC decides that women who have been harmed by their spouses get their dower.
-
 Entertainment4 months ago
Interim bail given to YouTuber Rajab Butt in gambling app marketing case
-
 Latest News4 months ago
A meta program to monitor mouse clicks made by employees in violation of EU privacy regulations