
Business
Oil prices rise on focus on supply recovery, demand

Oil prices rose slightly on Tuesday, but gains were limited as traders ignored lessening geopolitical tensions in the Middle East and focused instead on supply increases and demand predictions.
Brent crude futures were up 38 cents, or 0.5%, at $72.37 a barrel, and U.S. West Texas Intermediate crude increased 30 cents, or 0.4%, to $68.85 a barrel as of 0350 GMT, having closed Monday at about pre-Iran conflict levels.The moves toward recovery in supply have softened the immediate risk premium but the market remains hesitant of putting too much faith in the stability of the present truce given the on again off again nature of U.S.-Iran ties,” said Tim Waterer, chief market analyst at KCM Trade.We will be looking for early evidence of demand response, notably from China. “The market has priced in a lot of the good news on the supply side, so the next leg in oil prices will depend on whether the physical reality meets the optimistic headlines.
President Donald Trump said Monday the United States would either strike a deal with Iran or “finish the job,” reiterating his threat of military action as Tehran projected defiance after the funeral of former Supreme Leader Ayatollah Ali Khamenei.
Investors have been monitoring the health of ships via the Strait of Hormuz as they keep an eye on the progress of U.S.-Iran talks and the resurgence of Gulf oil exports.
Iran’s Revolutionary Guards launched at least two missiles at commercial ships traversing the Strait of Hormuz on Monday night, Axios said, citing two U.S. sources. The report indicated the commercial ships were badly damaged but there were no casualties.
Japanese-owned supertankers carrying Saudi Arabian crude headed on Tuesday to the Strait of Hormuz to leave the Gulf, shipping data revealed, joining a fleet of previously stranded vessels that escaped a day earlier.
Oil flow recovery is proving slower than predicted, ANZ analysts said in a report, despite the recent rise in strait activity.The first rebound in tanker transits across the Strait of Hormuz has stumbled, with vessel crossings continuing in single digits and no steady improvement in sight, they claimed.”The interim U.S.-Iran deal has diminished near-term geopolitical risks but shipping operators are still wary and curtail how quickly crude exports can return to normal levels.”
Meanwhile crude output from the United Arab Emirates topped more than 3.8 million barrels per day in June, its highest since April 2020 and beyond pre-Iran war levels, after it exited OPEC+ production limitations in May, according to Reuters estimates.
The Organization of the Petroleum Exporting Countries and allies including Russia agreed Sunday to raise output objectives by an additional 188,000 barrels per day from August, on top of comparable increases for June and July.
Saudi Arabia lowered the August official selling price (OSP) for its Arab Light crude to Asia by $1.50 a barrel below the Oman/Dubai average, a $11 fall from the previous month and the greatest cut in more than two decades, according to a Saudi Aramco pricing announcement on Monday.
Pakistan is the only major cotton-producing country to have had such a dramatic loss and its production has fallen by more than 60% in the past decade, said Ehsanul Haq, chairman of the Cotton Ginners Forum.
Haq added in a statement that lax enforcement of agricultural zoning laws, too much sugarcane planting in designated cotton-growing areas and setting up of new sugar mills were the main causes for the fall.
He urged on enforcement of crop zoning restrictions and preventing sugarcane cultivation in cotton belts to bring back local cotton production. He added after efficient execution of the zoning laws, enhancements should be made to cotton research stations and other supporting measures.
Haq further demanded to provide a legal structure to the planned Pakistan Cotton Board under the leadership of All Pakistan Textile Mills Association (APTMA. He advocated that the Pakistan Central Cotton Committee (PCCC) and its subordinate institutions should be placed under the proposed board.
The reduction in domestic cotton production and quality has created a crisis in the local cotton sector, making Pakistan more dependent on imported cotton and edible oil, putting more pressure on foreign exchange reserves, Haq said.
He claimed the government has failed to come up with a viable strategy to reverse the drop despite a high-level meeting chaired by the Deputy Prime Minister Ishaq Dar approximately a year ago, which decided to establish a cotton board under the direction of APTMA.
Signs have emerged that the decision has started to be implemented after a year of delay, he said.
The proposed board could include representatives of the Pakistan Cotton Ginners Association (PCGA), the Karachi Cotton Association (KCA), the Federation of Pakistan Chambers of Commerce and Industry (FPCCI), the National Textile Education Council, private seed companies and concerned government institutions.
Haq also called upon the federal and provincial governments to focus the enforcement of crop zoning restrictions and improve the Pakistan Meteorological Department so that it could deliver prompt and accurate weather forecasts to farmers.
“Cotton prices came under pressure last week due to financial difficulties in the sector, limited buying by textile mills, imports of yarn and fabric under the Export Facilitation Scheme and government inspections of cotton ginning factories,” he said.
Cotton prices fell to Rs18,500 from Rs18,500 per maund, a drop of Rs200, Haq said.
He also expressed concern over the reports of financial scandals involving billions of rupees in the yarn market of Faisalabad and millions of rupees in several cotton ginning facilities in Sindh, saying these developments have added to the uncertainty across the sector.
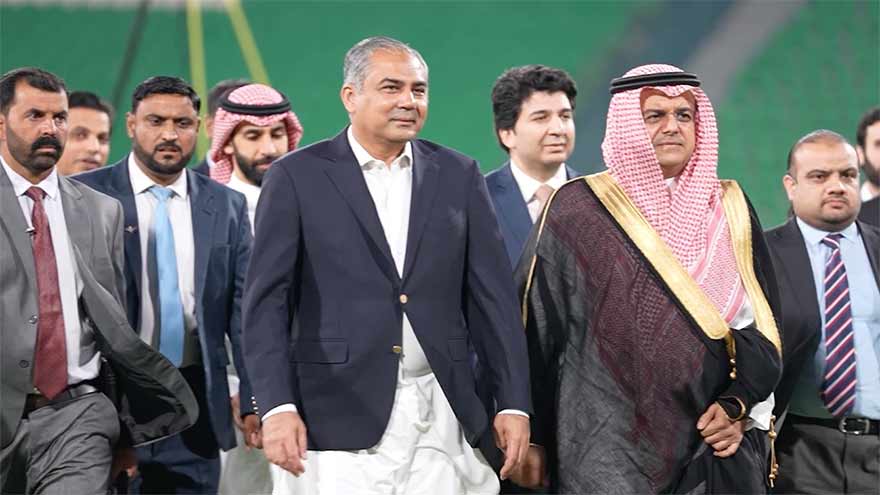
Saudi investors will fund a theme park in Islamabad, Pakistan’s interior ministry said on Sunday, in what it called a “first-of-its-kind” as Pakistan strives to attract foreign investment and construct new infrastructure.
The declaration came after Prince Mansour bin Mohammed Al-Saud, chairman of the Saudi-Pakistan Business Council (SPBC), and Sohail Ashraf, chairman of the Capital Development Authority (CDA), signed a memorandum of understanding (MoU) in Lahore, a city in the east of Pakistan.
The declaration comes as efforts to boost economic connections between Pakistan and Saudi Arabia are on the rise, with real estate, infrastructure and property development showing up as promising sectors for cross-border investments.
The deal for Pakistan’s first theme park project was signed in Lahore at Qaddafi Stadium in the presence of Interior Minister Mohsin Naqvi.
Under the deal Saudi Arabian investors will invest in the theme park project in Islamabad, the interior ministry stated. “The theme park is to be provided by CDA with land.
Mohsin welcomed signing of the MoU and said that the infrastructure of Islamabad was being constructed on the pattern of most contemporary cities of the globe.
He was cited as saying that “there are also plans to have a roadshow in Saudi Arabia in the coming months on real estate.”
“The theme park will be a game changing project,” Naqvi remarked. “All possible facilities will be provided to Saudi investors.
Earlier this week, three days of Saudi–Pakistan Real Estate Exhibition was held in Lahore, eastern city of Pakistan, showcasing real estate investment potential in the Kingdom.
The Pakistan Stock Exchange (PSX) began down on Monday as investors feared a possible hike in interest rates.
The benchmark KSE-100 Index fell almost 1,000 points to 161,250 points in early trade.
This latest fall followed a dismal close in the previous trading session when the KSE-100 Index lost 1,549 points to settle at 162,374 points.
Selling pressure remains in the stock market as investors fret about a likely interest rate hike, adding to uncertainty over how the market will perform.
The State Bank of Pakistan (SBP) Monetary Policy Committee will convene today to evaluate the country’s economic status and inflation prospects before declaring its monetary policy for the forthcoming quarter.
Amid recent tensions in the Middle East and growing pressure on the Pakistani rupee, economists and market watchers expect the central bank to hike the key policy rate by as much as 50 basis points.
The policy rate will go up to as high as 12 per cent from the present level of 11.5 per cent if the expected hike is executed.

Lula, Brazil’s iconic working class president, wins fourth term in dramatic comeback

Sahibzada Farhan replaces Saim Ayub in Pakistan ODI squad for tri-series matches

Pakistan’s cotton production plunges 60pc in a decade, says ginners’ chief

ICC board meeting in India: Mohsin Naqvi gets invitation

‘Self-Reliance in Digital ID’: NADRA launches locally produced QR code-based National Identity Card

23 people have died during the monsoon as rain-related incidents plague Punjab and KP.
-
 Latest News5 months ago
ICC board meeting in India: Mohsin Naqvi gets invitation
-
 Latest News2 months ago
‘Self-Reliance in Digital ID’: NADRA launches locally produced QR code-based National Identity Card
-
 Latest News3 months ago
23 people have died during the monsoon as rain-related incidents plague Punjab and KP.
-
 Latest News2 months ago
Turkish FM, Dar discuss regional trends, bilateral connections
-
 Business3 months ago
Govt dedicated to resolving Balochistan issues: Dar
-
 Latest News3 months ago
Pakistan making rapid progress in robotics, AI: Shaza Fatima
-
 Entertainment5 months ago
Interim bail given to YouTuber Rajab Butt in gambling app marketing case
-
 Latest News3 months ago
After a divorce, LHC decides that women who have been harmed by their spouses get their dower.